
How AI and Analytics Are Replacing Old School Payment Fraud Detection in Australia

A fraudulent payment does not end when the transaction is declined or refunded. For an Australian business, the real cost can spread across chargeback fees, lost stock, staff time, higher payment processing costs, false declines, customer frustration and gaps in financial reporting.
That is why payment fraud detection is shifting from manual checks and static rules to AI and analytics. The old approach looked for obvious red flags, such as a large order, a mismatched address or too many attempts on one card. That still catches some fraud, but it misses the wider pattern.
Modern fraud is faster, more automated and harder to spot one transaction at a time. AI systems can scan thousands of signals at once, compare behaviour across channels and flag anomalies before the loss becomes visible in the accounts.
In this post we look at how AI and Analytics are replacing old school payment fraud detection in Australia
Payment fraud is now a cost problem, not just a risk problem
Australian businesses lose money to payment fraud in more ways than the obvious stolen-card transaction. The loss usually stacks up in layers.
A disputed card payment can mean:
The original sale is reversed
The goods or service are already delivered
The payment provider charges a dispute or chargeback fee
Staff spend time gathering evidence
The merchant may face higher monitoring or processing costs
Too many disputes can affect access to payment services
Then there are scams, account takeovers, refund abuse, first-party fraud and internal process leaks. Each one hits the business differently.
There is no single public number that captures the full cost of payment fraud to Australian businesses. The reason is simple. Losses sit across banks, card networks, merchants, marketplaces, payment processors, insurers, logistics providers and customers. Some fraud is reported. Some is written off. Some is buried inside “customer service”, “refunds”, “bad debt” or “shrinkage”.
What is clear is that the bill is large. Public Australian scam and cybercrime reporting regularly shows losses in the billions across the economy. Businesses also carry the indirect cost of fraud prevention, compliance, staff investigation time and revenue lost through good customers being blocked.
For many merchants, the painful part is not one big fraud event. It is the slow leakage: small refund abuse, repeated low-value disputes, voucher misuse, fake accounts, mule accounts, delivery manipulation and suspicious payment patterns that never get reviewed because each item looks too small.
That leakage can quietly erode margins.
Where the money leaks out
Payment fraud often looks like a technology issue, but many losses come from broken handoffs between systems. Payments, orders, refunds, fulfilment, customer support and finance all hold part of the truth. If those systems do not talk to each other well, fraud hides in the gaps.
Leakage area | What it looks like | How AI and analytics help plug it |
Chargebacks | Customers or fraudsters dispute transactions after goods are shipped | Score dispute risk before fulfilment and gather evidence automatically |
Account takeover | A real customer account is used with changed shipping or payment details | Detect unusual login, device, location and spending behaviour |
Refund abuse | Repeated refund claims, partial returns or “item not received” patterns | Link refund history across accounts, cards, devices and addresses |
False declines | Good customers are blocked by blunt rules | Use risk scoring instead of automatic rejection |
Friendly fraud | A customer claims a valid purchase was unauthorised | Compare purchase history, delivery proof and customer behaviour |
Internal leakage | Manual overrides, duplicate refunds or process exceptions | Flag unusual staff actions and repeated exception patterns |
Promo and voucher misuse | One person uses many accounts to exploit offers | Detect shared devices, addresses, payment instruments and behavioural clues |
The key point is that fraud is not always a single bad transaction. It is often a pattern across many normal-looking events.
A customer who requests one refund may be genuine. A customer who requests five refunds across different accounts, with similar delivery claims and linked devices, deserves a closer look. A single high-value order may be fine. A high-value order placed minutes after a password reset, from a new device, with express shipping to a new address, may carry real risk.
Old systems struggle with that level of context.
Why old school fraud rules are getting expensive
Traditional fraud detection relies heavily on static rules. For example:
Block transactions above a set dollar amount
Review orders from certain countries
Decline payments after several failed attempts
Hold orders with different billing and shipping details
Manually check high-risk orders before shipping
These rules made sense when payment channels were simpler. They are easy to understand and easy to audit. They still have a place, especially for clear policy controls.
The problem is that rules age badly.
Fraudsters test them. If a merchant blocks orders above $1,000, fraudsters try $980. If velocity checks look at five attempts in ten minutes, bots slow down. If address mismatch triggers review, fraudsters target digital goods or click-and-collect flows.
Rules also create too many false positives. A genuine customer buying a gift and shipping it to a relative can look suspicious. A traveller using a new device can look risky. A loyal customer making an unusually large purchase can get blocked.
Every false decline has a cost. The business loses the sale, may lose the customer and still pays for the tools and staff that created the friction.
Manual review also becomes expensive as volume grows. A team can check a handful of suspicious orders. It cannot sensibly review every odd pattern across cards, wallets, PayTo, account-based payments, subscriptions, refunds and support requests.
That is why old school methods are becoming less viable. They cost more each year, yet catch less of the fraud that matters.
How AI changes fraud detection
AI does not replace every fraud control. It changes the way risk is scored.
Instead of asking, “Did this transaction break a rule?”, AI-driven systems ask, “How similar is this behaviour to known good activity, known bad activity and emerging suspicious patterns?”
That shift matters.
A good fraud model can assess signals such as:
Transaction amount and timing
Payment method
Device fingerprint
Location and network details
Customer history
Login behaviour
Cart contents
Shipping choice
Refund and dispute history
Failed payment attempts
Links to other accounts
Behaviour during checkout
No single signal proves fraud. The power comes from the combination.
For example, a $600 transaction may not be risky by itself. A $600 transaction from a new device, after multiple failed login attempts, with a newly added card, shipping to a new address, placed at 2 am and followed by a request to change delivery instructions looks different.
AI can catch that combination faster than a human reviewer. More importantly, it can rank risk at scale.
That allows businesses to treat payments in tiers:
Low-risk transactions pass with little friction
Medium-risk transactions trigger extra checks
High-risk transactions are held, challenged or declined
Suspicious patterns are sent for investigation
This approach protects revenue as well as reduces fraud. Good customers are less likely to be blocked by one rigid rule.

Analytics finds the fraud that rules miss
AI models are useful, but analytics gives them direction. Analytics shows where the leakages are, how fraud is changing and whether controls are working.
A strong payments risk program tracks more than the fraud rate. It also monitors:
Chargeback rate
This shows how often transactions turn into disputes. It should be segmented by product, channel, payment type, customer type and fulfilment method.
Refund rate
A rising refund rate may signal product issues, service problems or abuse. The difference matters.
Manual review rate
If too many transactions need human review, the model or rules may be too blunt.
Approval rate
A fraud system that blocks too many good payments can hurt revenue.
False positive rate
This is one of the most overlooked costs. A safe transaction declined by mistake is still a loss.
Time to detect
Fraud found after fulfilment is far more expensive than fraud caught before shipment or service delivery.
Dispute win rate
Strong evidence, clean data and fast response can improve outcomes when chargebacks occur.
Analytics also helps teams see repeat patterns. For example, a business may find that fraud clusters around a particular delivery method, sales campaign, product category or refund policy. That discovery can lead to a practical fix, such as requiring stronger verification for certain orders or tightening refund workflows.
The best results come when analytics is tied to operations. A dashboard alone does not stop fraud. A dashboard that triggers better decisions can.
What a modern AI and analytics setup looks like
A modern payment fraud program does not need to be huge, but it does need clean data and clear decision points.
The basic structure usually looks like this:
Collect the right data
Bring together payment, order, customer, device, fulfilment, refund and dispute data. Fraud hides when these records stay separate.
Create a risk score
Use models and rules together. AI handles pattern detection. Rules still handle business policies, compliance controls and hard stops.
Apply the right action
Do not treat every flagged payment the same way. Some need step-up authentication. Some need manual review. Some should be declined. Some should pass.
Feed outcomes back into the model
Confirmed fraud, successful chargebacks, lost disputes, genuine transactions and false declines should all improve future decisions.
Monitor drift
Fraud patterns change. A model trained on last year’s behaviour can lose accuracy if it is not checked and updated.
Keep humans in the loop
Analysts still matter, especially for edge cases, policy decisions and emerging fraud types. AI does the scanning. People decide how the business should respond.
This is where many businesses go wrong. They buy a tool but do not fix the process around it. The result is another alert queue, not better fraud control.
Chargebacks need evidence, not panic
Chargebacks are one of the most visible payment fraud costs because they come with paperwork and deadlines. They also create operational noise.
A strong chargeback process starts before the dispute arrives.
Businesses can improve their position by keeping:
Clear transaction records
Device and IP evidence where legally and contractually allowed
Delivery confirmation
Customer communication history
Refund and return records
Terms accepted at checkout
Proof of service usage for digital products
AI and analytics can help gather and rank this evidence. For example, if a customer claims a payment was unauthorised, the system can quickly show whether the same device was used before, whether the shipping address matches past orders, whether the customer used the product and whether similar disputes came from linked accounts.
This does not guarantee a dispute win. Card scheme rules, payment method rules and consumer protections still apply. It does reduce the chance that valid evidence is missed because staff are rushing.
For Australian businesses, that matters. Chargeback management is rarely someone’s only job. It is often handled by finance, customer service, operations or a small risk team. Better evidence handling saves time and protects revenue.
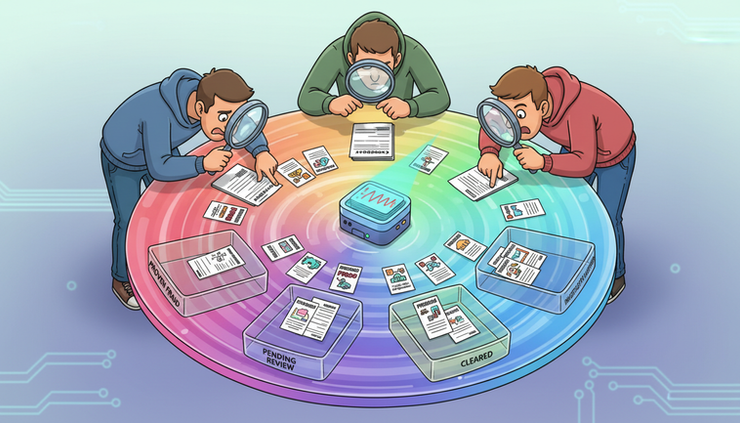
How businesses can plug payment leakages
The practical fix is not “add AI” and hope for the best. The fix is to find the main leakage points, then match controls to them.
Start with the places where money leaves the business after the sale.
For chargebacks
Track disputes by reason code, product, channel and customer segment. Automate evidence collection where possible. Use pre-fulfilment risk scoring for orders that are expensive, fast-shipped or difficult to recover.
For refund abuse
Link refund requests to customer history, delivery records, devices and payment instruments. Look for repeated patterns rather than isolated claims.
For account takeover
Monitor login behaviour, password resets, new devices, new addresses and rapid changes before purchase. Use step-up checks when behaviour changes sharply.
For false declines
Review declined transactions that later appear genuine. Test whether rules are too strict. A small lift in approval rates can recover real revenue.
For internal process gaps
Monitor manual overrides, duplicate refunds, high exception rates and unusual activity by role. Most leakage is not malicious. Some of it comes from unclear workflows.
For marketplace or multi-location businesses
Compare fraud and refund patterns by seller, store, region and fulfilment type. Outliers often reveal weak controls.
Modern tools make this easier because they can connect events across the payment lifecycle. That is the real advantage. Fraud prevention stops being a gate at checkout and becomes a feedback loop across the business.
Why obsolete does not mean useless
Old school methods will not disappear overnight. Static rules, manual checks and basic velocity controls still catch simple fraud. They are also useful for governance because they are easy to explain.
The issue is that they cannot carry the full load anymore.
As payment options expand and fraudsters automate their testing, fixed rules become more expensive to maintain. They create review queues, frustrate good customers and miss patterns that sit across accounts, refunds, devices and fulfilment.
AI and analytics are taking over because they are better suited to the shape of modern fraud. They learn from patterns, adjust faster and help teams focus attention where the risk is highest.
The businesses that benefit most will not be the ones with the fanciest model. They will be the ones that treat fraud as a measurable operating cost, connect their data and keep improving the decisions around each payment.
This article is general information only and does not replace legal, financial or payments compliance advice.
Payment fraud will keep changing. The strongest defence is a system that changes with it, catches leakage early and protects genuine customers while making fraud harder, slower and less profitable.


Comments